A deal that reignites an old argument
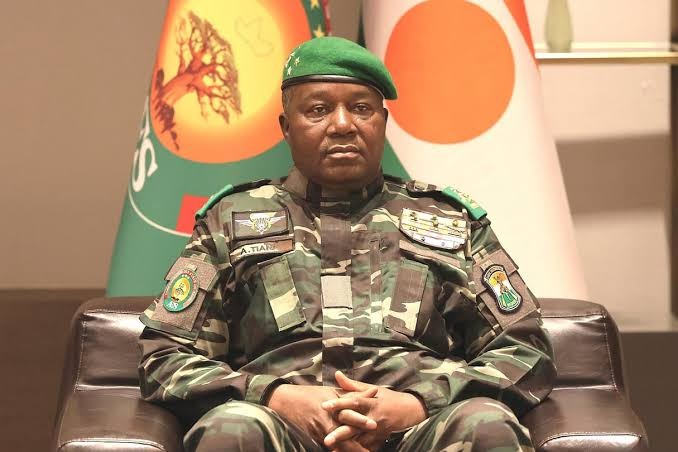
When the transitional authorities in Niamey made national sovereignty and the rejection of foreign oversight centrepieces of their political programme, few expected the public purse to force such a swift reckoning. On Thursday 8 October 2026, the International Monetary Fund announced that a staff-level agreement had been reached following a mission to Niamey led by Julia Bersch between 28 September and 8 October 2026. The announcement has reopened a heated conversation across the country about what economic independence actually means in practice.
What the new 38-month arrangement involves
Far from the rhetoric of self-sufficiency and rupture, Niamey has just completed the tenth and final review of its existing programme and committed to an entirely new one under the Extended Credit Facility. Running for 38 months, this fresh financial arrangement unlocks a total of 150.02 million Special Drawing Rights — roughly $203 million, or about 114 per cent of the country’s quota.
Subject to approval by the IMF’s executive board expected in early December 2026, an initial disbursement of 26.3244 million SDRs, around $36 million, will be released urgently to replenish public coffers and cover external financing needs.
Oil revenues versus the cost of daily life
The government led by Prime Minister Ali Mahaman Lamine Zeine has published flattering macroeconomic forecasts: GDP growth projected at 7 per cent in 2026, then 6.7 per cent in 2027 and an average of 6.1 per cent over the medium term, driven by agriculture and above all by soaring crude oil exports. Inflation, estimated at -2.5 per cent in 2026 before rising to 2.2 per cent in 2027, nonetheless masks a dramatic increase in transport costs linked to the diplomatic and security climate, which is hitting the most vulnerable households hardest.
Yet despite the oil windfall and rising world prices, the national budget remains in deficit, projected at 3.4 per cent of GDP for 2026. Burdened by post-disaster reconstruction spending, emergency subsidies and an overwhelming security bill, Niger cannot finance its ambitious Programme for the Refoundation of the Republic (2025–2029) without the backing of international financial institutions.
The contradiction at the heart of the refoundation agenda
The IMF makes no secret of it: the new programme will require continued deep structural reforms, ranging from stronger tax capacity to public debt discipline and financial sector reform.
This heavy reliance on the Extended Credit Facility mechanisms exposes a major political contradiction. While official messaging works hard to convince audiences of the country’s reclaimed sovereignty, the day-to-day management of the treasury proves that Niger’s economy remains dependent on international financial orthodoxy. It is a budgetary reality that reminds observers that genuine autonomy is not proclaimed from a podium — it is built on a state’s real capacity to finance its own development.
Reactions on the ground and in the commentary
The announcement has provoked a mixed response. Supporters of the programme argue that the funding is indispensable given the scale of reconstruction needs and security spending, and that refusing it would only deepen hardship for ordinary citizens. Critics, by contrast, see a glaring inconsistency between the sovereignty discourse and the conditions attached to the new credit line, warning that structural reform commitments could constrain future budget choices.
Economists and civil society voices have also raised questions about transparency: how the disbursed funds will be allocated, whether priority will be given to social spending, and how the government intends to reconcile reform targets with its stated political vision.
What comes next
All eyes are now on the IMF executive board meeting expected in early December 2026, which must sign off on the arrangement before the first tranche can be released. Beyond that, the coming months will test whether Niamey can use the breathing space to strengthen domestic revenue mobilisation and reduce its reliance on external financing.
The bigger question — whether a country can pursue a refoundation agenda while operating under an IMF programme — will not be settled by communiqués. It will be answered by budget choices, by the living standards of Nigerien households, and by whether the promised reforms translate into tangible improvements or simply into another cycle of dependency.